THE CAPITAL GAIN QUESTION
When a family sells their residential flat in Delhi’s Lutyens
bungalow zone for ₹6 crore, the Stamp Duty Value (SDV) is ₹8 crore.
Under Section 50C of the Income Tax Act, the ₹8 crore
SDV is deemed to be the full value of consideration for capital gain
purposes — unless the seller can demonstrate, through a
Government Approved Capital Gain Valuer’s certificate,
that the FMV on the date of transfer was below the SDV.
The same family’s estate includes a
Mughal gold jewellery set acquired in 1985
and a Husain canvas from 1993: for both, the
Section 55(2)(b) substitution allows the
FMV as on 1 April 2001 to be treated as the cost
of acquisition — substituting a higher base than the 1985 and 1993
original purchase prices and reducing the taxable gain.
The Finance Act 2024’s restructuring of LTCG rates
to 12.5% without indexation from 23 July 2024
makes the transitional computation — comparing 12.5% without
indexation vs 20% with indexation using the
CII series from the 1 April 2001 base — the most
important capital gain planning calculation for pre-2024 acquisitions.
All three require a
Section 34AB Government Approved Capital Gain Valuer’s
certificate: the Section 50C FMV challenge; the
Section 55(2)(b) 1 April 2001 base value; and the pre-23 July 2024
FMV for the transitional computation.
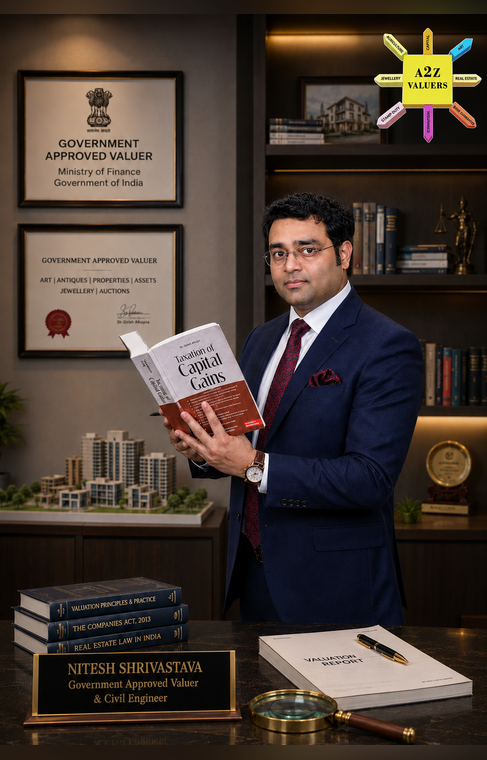
A2Z Valuers under Nitesh Shrivastava — Civil Engineer,
Government Approved Valuer — produces all three, across
all asset classes, under a single
multi-asset engagement. Appointed by the
Income Tax Department for PAN India enforcement
valuations.
The practice that valued the
₹50+ crore Mughal jewellery and colonial Indian art
for India’s top auction house in 2025.
250+ professional valuation services across India.
PAN India.